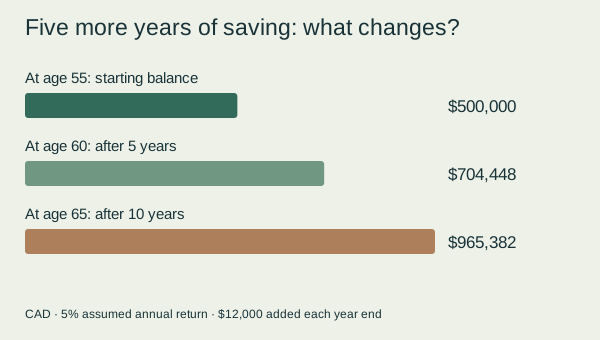
FinancialMirror.ca

YOUR LIFE. SEEN MORE CLEARLY.

Your financial reality.
Reflected honestly.

We build your plan around your actual financial situation, with detailed, automated calculations that account for taxes and make assumptions clear. No inflated projections. No false promises.

Detailed calculations. Visible assumptions. Honest guidance.

A QUESTION. A CALCULATION. A CLEARER PICTURE.

Illustrative savings balances at age 55, 60 and 65.
Saving longer changes the starting point. Whether retirement is affordable also depends on spending, pensions, taxes and risk.
See the calculation and assumptions

Fictional savings example: $500,000 at age 55; $12,000 added at each year end; fixed nominal 5% annual return. Each year: previous balance × 1.05 + $12,000. Dollar labels are rounded. Excludes taxes, fees, inflation and withdrawals. Returns are not guaranteed.

Retirement & incomeFamily & protectionBusiness-owner planningLegacy & next generations

THE FINANCIALMIRROR MISSION

The difference
is in the details.

We truly mirror your financial situation and plan for the future accordingly. That commitment guides our analysis, our software and every conversation.

See how we work ↗

Your reality comes first.

We don’t leave out costs or inconvenient details to make the numbers look better. We connect income, taxes, investments, insurance and estate considerations into a detailed financial picture.

Honest expectations. Clear choices.

No inflated projections. No false promises. A clear view of where you stand, what your choices could mean, and how to prepare for the future.

Every assumption visible. Every calculation traceable. Every tradeoff explained.

START WITH A REAL QUESTION

Life doesn’t fit into
a single spreadsheet.

Real decisions involve taxes, costs and tradeoffs. These fictional households show how we bring the details into the conversation—even when the numbers challenge the original plan.

01 / RETIREMENT
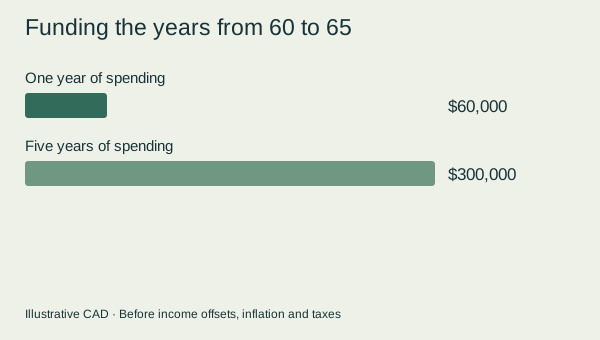
One year of spending: $60,000. Five years: $300,000.

MEET MAYA & DANIEL · AGES 52 & 54

“Could we retire sooner
and still feel secure?”

They have savings and a paid-down mortgage. What they don’t have is a clear picture of how long their money needs to last.

Explore their planning conversation

What we would calculate

The chart isolates one question: five years of $60,000 annual spending is $300,000. This is a gross spending bridge, before pensions, other income, inflation and taxes. A full comparison would calculate household cash flow, pensions and withdrawals.

What we would test

Lower returns, higher living costs, a longer retirement and the financial impact of one partner dying first.

The decision we would guide

Whether retiring earlier, working part-time or adjusting spending offers the balance they value.

Talk about your retirement →
02 / BUSINESS OWNERS
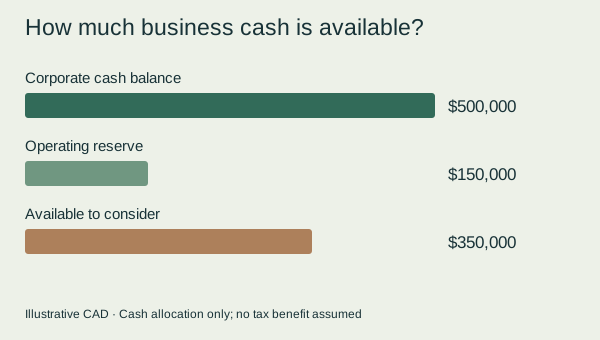
Cash $500,000 less reserve $150,000 leaves $350,000.

MEET AMIR · AGE 46

“My business is growing.
Is my personal future?”

Money is building inside his corporation. He wants to understand how it could support his family, retirement and long-term goals.

Explore his planning conversation

What we would calculate

The example starts with $500,000 corporate cash and sets aside a $150,000 operating reserve: $350,000 remains to consider for other goals. This is cash allocation, not a recommended strategy. We would compare suitable options with taxes, liquidity and cash-flow effects included.

What we would test

Changes in business cash flow, investment returns and borrowing costs where a strategy involves financing.

The decision we would guide

How to balance accessible cash, future income, protection and estate goals alongside his accounting and legal professionals.

Talk about your business and future →
03 / FAMILY PROTECTION
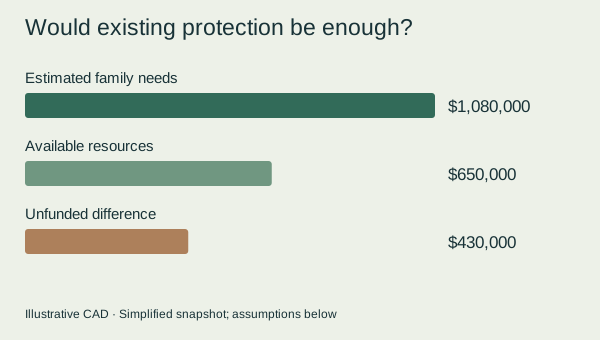
Needs $1,080,000 less resources $650,000 leaves a $430,000 gap.

MEET SOPHIE & ALEX · TWO YOUNG CHILDREN

“Would our family be okay
if life changed tomorrow?”

A mortgage, two incomes and education goals. They want to know what their existing protection would actually cover.

Explore their planning conversation

What we would calculate

Example needs: $60,000 annual support for 10 years ($600,000), $400,000 mortgage repayment and $80,000 education funding: $1,080,000 total. Resources: $150,000 available savings plus $500,000 existing insurance: $650,000. Difference: $430,000. This simplified snapshot excludes discounting, inflation, taxes, survivor income and benefits. A full assessment would account for these and avoid counting repaid mortgage costs again in support needs.

What we would test

Loss of either income, changing childcare needs and different protection budgets.

The decision we would guide

The amount and type of protection that fits their needs, affordability and time horizon, with alternatives explained.

Talk about your family’s priorities →

All chart amounts are fictional CAD examples, not completed financial plans or guaranteed outcomes. Open each planning conversation to see the context and assumptions.

THOUGHTFUL PROCESS. UNDERSTANDABLE ANSWERS.

From “what if?”
to “what’s next?”

A useful plan reflects your reality. We make the calculations, assumptions and tradeoffs understandable, so your next steps are grounded in the full picture.

Start with your question ↗
  1. 01

    Understand your whole picture.

    Start with your priorities and actual financial position. Connect income, savings, obligations, business interests and the people who depend on you. Identify missing information before treating it as fact.

  2. 02

    Calculate the possibilities.

    Automate detailed calculations and compare suitable choices under consistent assumptions. Account for applicable taxes and costs, and show where uncertainty or missing inputs affect the answer.

  3. 03

    Choose a direction. Revisit it.

    Explain the findings—including shortfalls and inconvenient tradeoffs—then agree on practical next steps. Revisit the plan as your circumstances and assumptions change.

WHO WE ARE

Real people.
A shared focus on your future.

Meet Soroush Lessan and Tara Faraji, the Financial Planners behind FinancialMirror. Start with your questions. Explore the possibilities together.

Meet Soroush & Tara ↗

FOR FINANCIAL ADVISORS

Depth behind the numbers.
Clarity in the conversation.

Our sophisticated software infrastructure connects detailed calculations across retirement, insurance, business-owner strategies and family needs. Make tax effects and assumptions visible, compare choices consistently, and present the findings honestly—even when a scenario needs rethinking.

Ask about an advisor demonstration ↗
THE ADVISOR WORKSPACE
  • 01 Household & retirement planning
  • 02 Insurance & policy comparisons
  • 03 Corporate-owner scenarios
  • 04 Clear client presentations

Precision in the calculations. Transparency in the assumptions. Clarity in the conversation.

A GUIDED LOOK INSIDE OUR SOFTWARE

From a household picture
to a considered decision.

Follow an advisor through a fictional household: enter income, review savings and family details, calculate a plan, then explore retiring five years earlier.

FINANCIALMIRROR · SOFTWARE WALKTHROUGH82 SECOND GUIDED TOUR
Preparing the walkthrough…
0:00 / 1:22
01 / START WITH THE HOUSEHOLD

One connected financial picture.

A wider view of the actual interface. Press play to follow the advisor’s workflow.

Guided interface replay with results captured from the actual calculation engine. Fictional household; model assumptions and limitations remain visible in the software. Playback is paced for explanation and does not measure computation speed.

YOUR NEXT CHAPTER STARTS WITH A CONVERSATION

What would you like
to see more clearly?

Bring us your questions and your actual situation. We’ll help you understand the choices ahead, with clear numbers and honest expectations.

Let’s start a conversation ↗Please keep your first email general; don’t include account numbers or financial documents.